Official Letter No. 2265/CST-GTGT: Enhanced scrutiny for the application of the 0% VAT rate to exported services
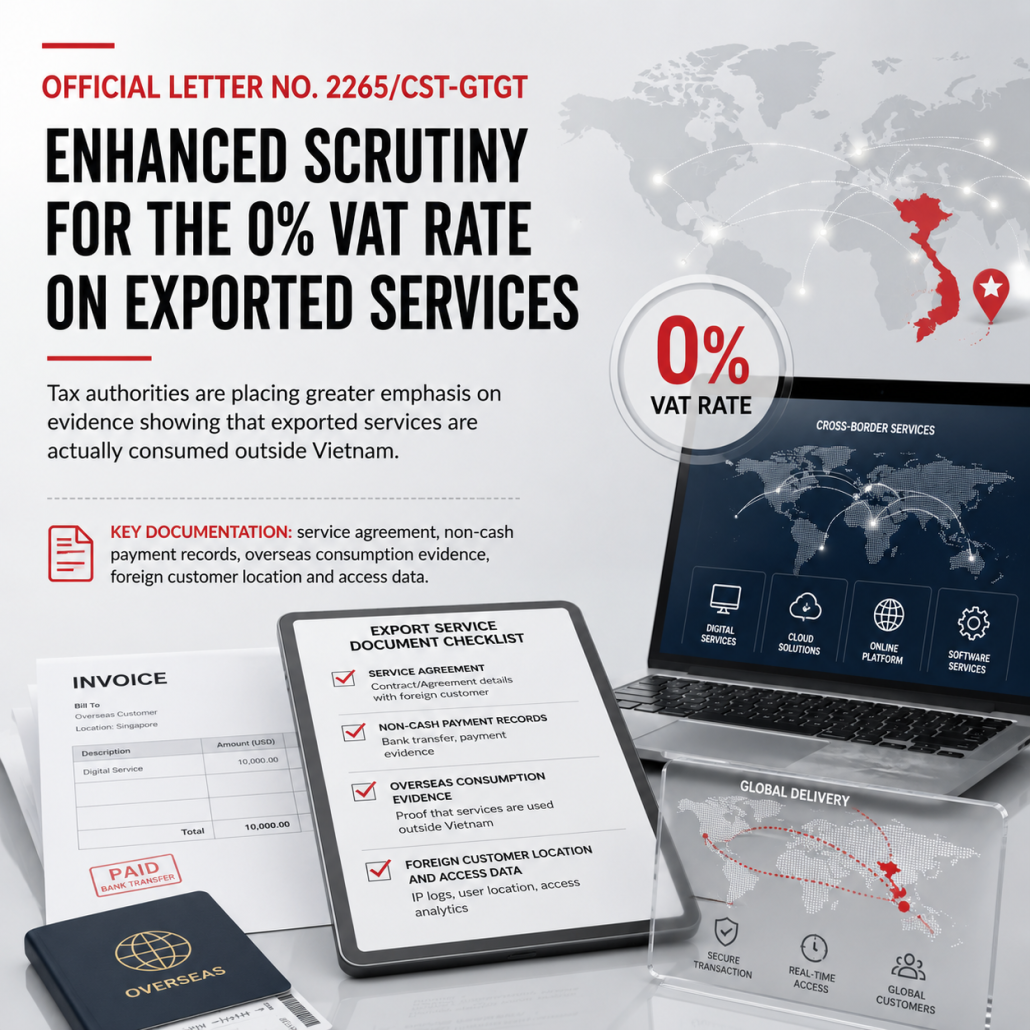
On 4 August 2026, the Department of Tax, Fee and Charge Policy Management and Supervision issued Official Letter No. 2265/CST-GTGT (“Official Letter 2265”), providing guidance on supporting documents required to substantiate eligibility for the 0% VAT rate applicable to services supplied to foreign organizations and individuals and consumed outside Vietnam.
The documentation requirements differ depending on when the relevant transactions arise, as follows:
For exported services arising before 1 July 2025
For transactions arising before 1 July 2025, businesses are required to provide:
- a service provision agreement;
- bank payment documents; and
- documents evidencing that the services were performed outside Vietnam.
For exported services arising from 1 July 2025
For transactions arising from 1 July 2025, businesses are required to provide:
- a service provision agreement with the relevant foreign organization or individual;
- non-cash payment documents; and
- other supporting documents as may be required by the competent State authorities.
Accordingly, in certain cases, the tax authorities may require businesses to provide additional documents and information to verify their eligibility for the 0% VAT rate.
Particular attention should be paid where a business supplies digital information content products to a foreign customer, such as text, data, images or audio in digital form that are stored or transmitted over a network environment. For these products, businesses must retain and provide documents and information evidencing that the products are consumed outside Vietnam, including:
- information regarding the foreign customer’s residence or location, such as billing address, delivery address, registered office address, residential address or other similar information; and
- information evidencing access from outside Vietnam, such as the country calling code associated with the SIM card, IP address, location of a fixed telephone line or other similar information.
Official Letter 2265 therefore indicates increased scrutiny by the tax authorities over the eligibility for the 0% VAT rate applicable to exported services, with greater emphasis on specific and substantive evidence demonstrating that the relevant services are actually consumed outside Vietnam, rather than relying solely on contractual and payment documentation.
In this context, businesses providing services to foreign customers should review the supporting documentation for transactions currently subject to the 0% VAT rate and maintain sufficient records evidencing the provision and consumption of such services outside Vietnam. For digital information content products, businesses should also establish mechanisms to collect and retain information regarding the foreign customer’s residence or location and access from outside Vietnam, so that such information can be readily provided to the tax authorities upon request.




